
Jon Peddie Research reports that worldwide PC client CPU shipments fell to 60.8 million units in Q3’26, down -3.4% from the previous quarter and -6.5% from a year earlier. Integrated GPU shipments declined to 54.9 million units, down -3% sequentially and -3.8% year over year. Server CPU shipments reached 8.13 million units, continuing their upward trend.
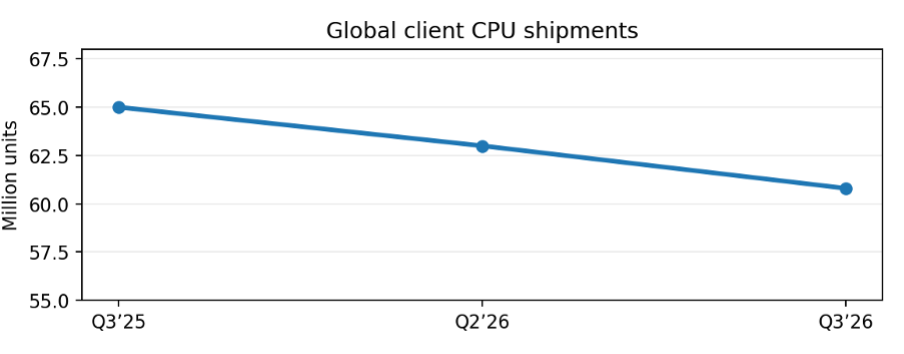
Figure 1. Global client CPU shipments fell to 60.8 million units in Q3’26. (Source: JPR)
The client market weakened after Q2’s inventory rebuilding. Intel’s client computing segment reported $8.1 billion in revenue, down -5% year over year and approximately -9% from Q2’s $8.88 billion. CFO Dave Zinsner expects the PC slowdown to continue through at least the first half of 2027, which may keep OEM inventories lean.
The desktop market declined -13% year over year, while notebook CPU shipments fell -4%. The DIY channel remained weak after gamers advanced purchases into Q4 2025 ahead of anticipated memory and SSD price increases. Intel continued ramping Panther Lake, while AMD expanded Ryzen AI Max Pro 400 systems.
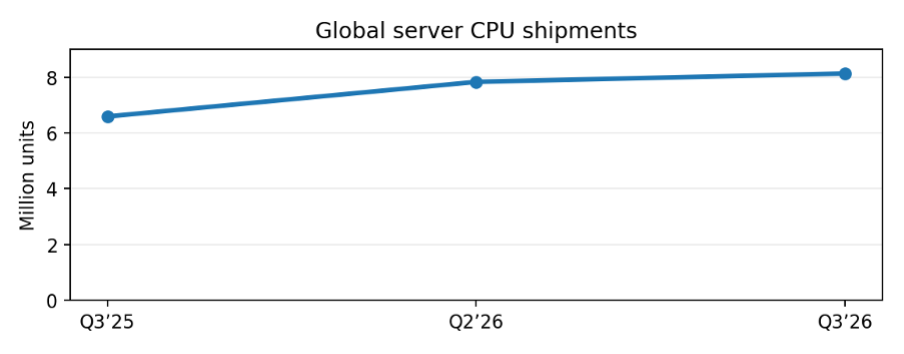
Figure 2. Server CPU shipments reached 8.13 million units; AMD held 34.1% share. (Source: JPR)
Server CPU shipments reached 8.13 million units in Q3’26, compared with 7.83 million in Q2’26 and 6.59 million in Q3’25. AMD increased its unit share to 34.1%, versus Intel’s 65.9%. Server demand continued to exceed supply, with agentic AI supporting unit growth and a higher-value product mix.
The global integrated GPU market declined from 56.6 million units in Q2’26 to 54.9 million in Q3’26, compared with 57.1 million a year earlier. AMD accounted for 23% of Q3 iGPU shipments and Intel for 77%. The preview also notes that the ratio of GPUs to CPUs increased in cloud inference, even as data centers continued to deploy CPUs.
“Client CPU shipments softened in Q3 as OEMs kept inventories lean and the DIY channel remained weak,” said Dr. Jon Peddie, president of Jon Peddie Research. “Server CPUs continued growing, with AMD gaining share and AI-related demand supporting the market. We expect PC conditions to remain difficult into the first half of 2027.”
Pricing and availability
JPR’s Overview of PC Client CPUs and iGPUs report is available free to Market Watch subscribers and can be purchased separately for $250.
The Q3’26 edition of Market Watch will include these results and additional analysis. The report uses a chart-based presentation and provides historical server and client CPU shipment data and GPU-compute (GPGPU) shipment data for AMD, Intel, and Nvidia dating to Q1’21, with corresponding pivot data.
A single issue of JPR’s Market Watch sells for $3,000. This report includes an Excel workbook with the data used to create the charts, the charts themselves, and supplemental information. The annual subscription price for JPR’s Market Watch is $6,000 and includes four quarterly issues.
Click here to view the table of contents and more related to this significant report or to download it now. For more information, call (415) 435-9368 or visit the Jon Peddie Research website at www.jonpeddie.com.
JPR is now offering two new reports on AI coprocessors and RISC-V processors.
JPR also publishes a series of reports on the graphics add-in board market, the workstation market, and PC gaming hardware market. The latter covers the total market, including systems and accessories, and examines 31 countries.
Full subscribers to JPR services receive TechWatch (the company’s exclusive access to daily news).